All Categories
Featured

Current Term Life Insurance Prices for Families
Table of Contents
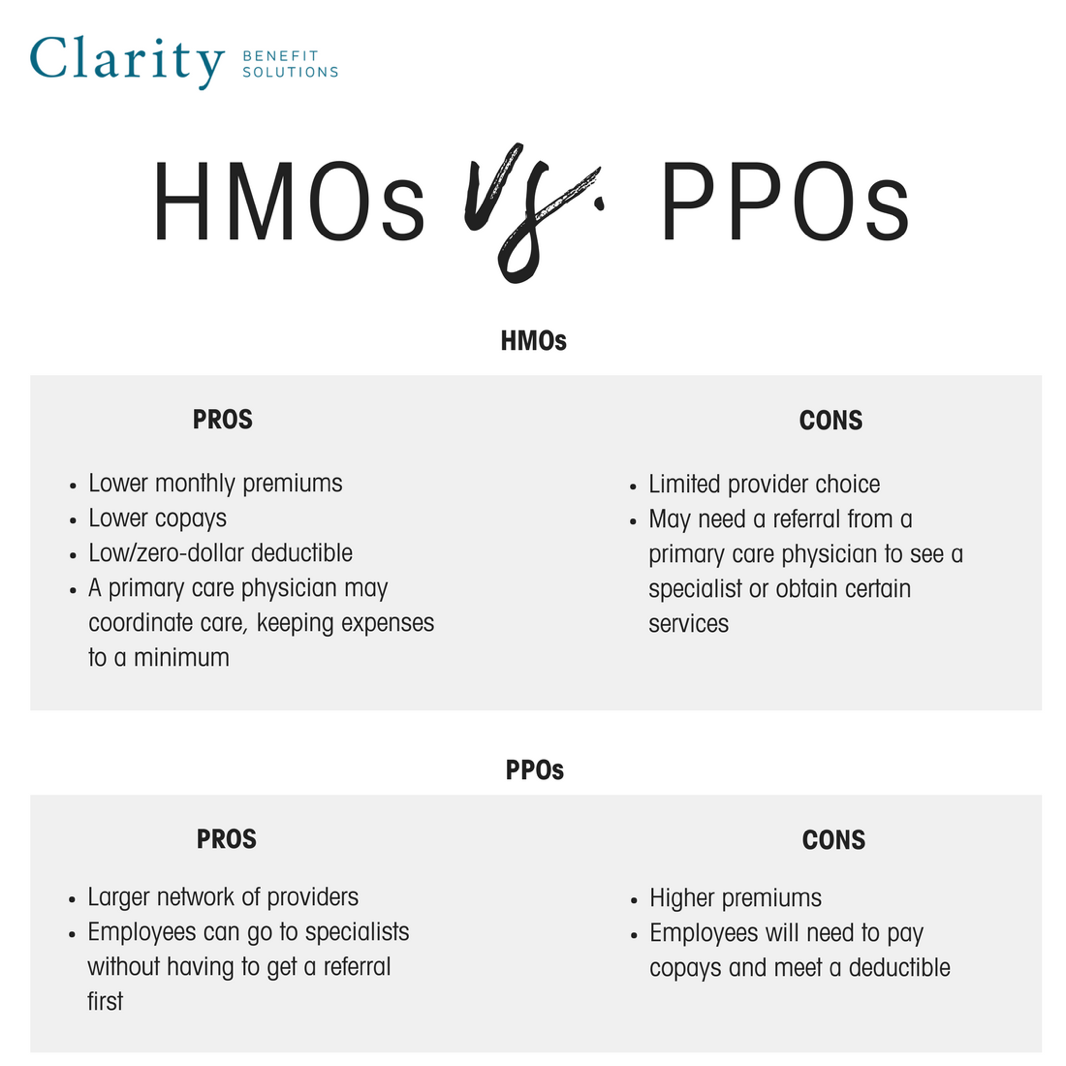
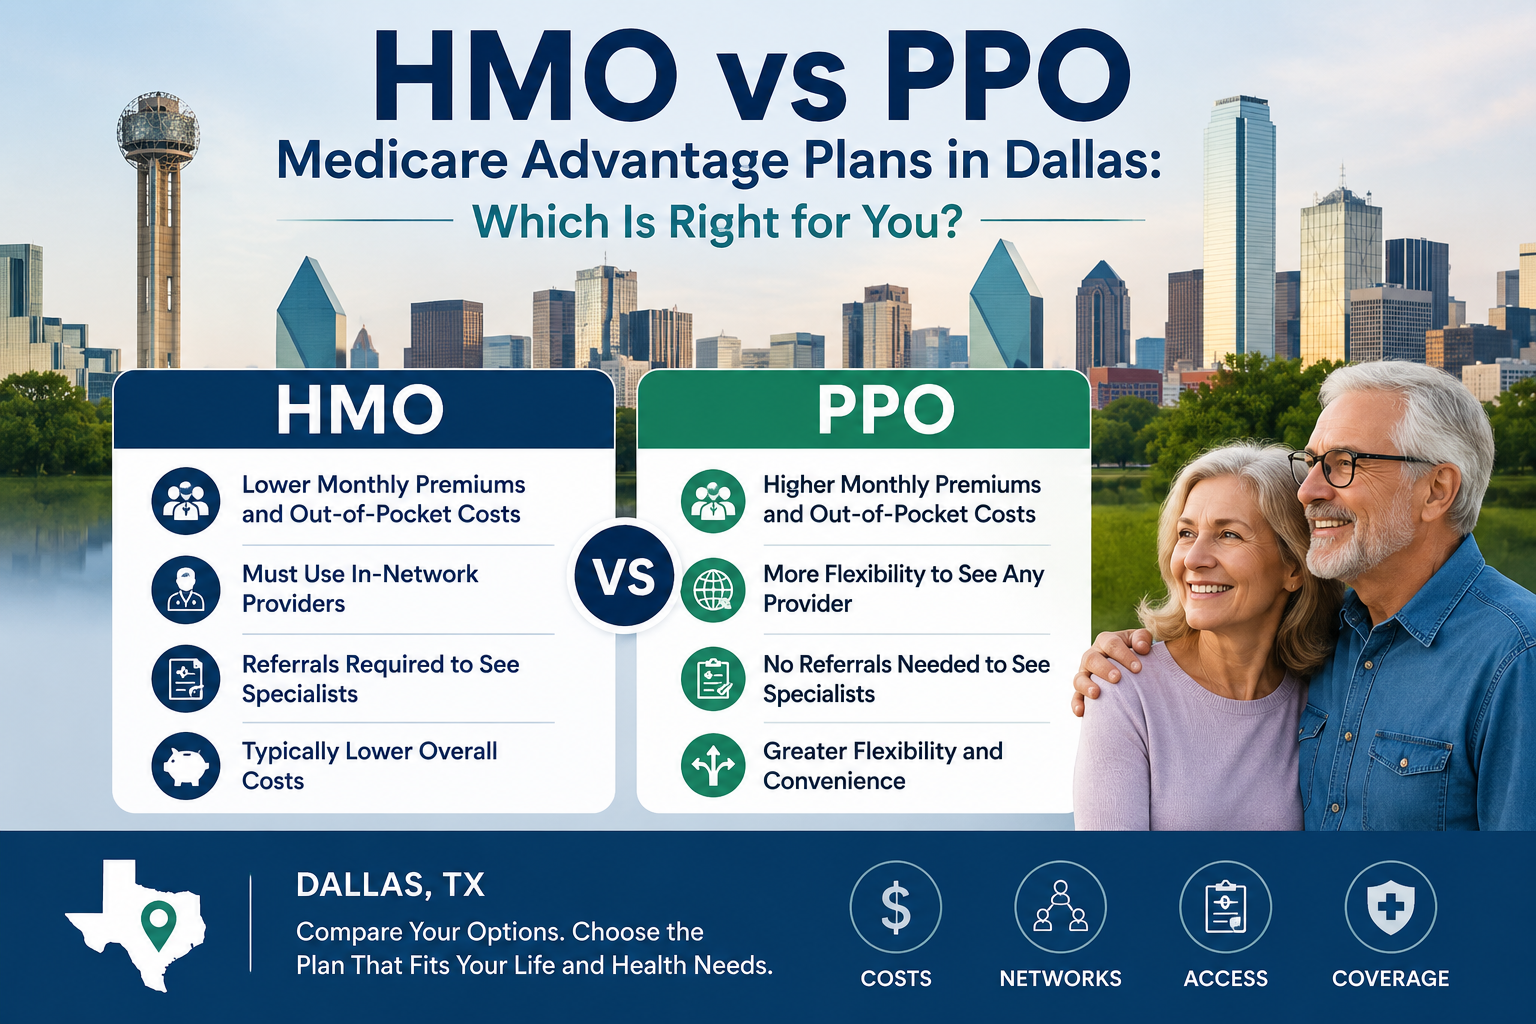
Like all health insurance, receiving in-network care is best to keep your out-of-pocket costs low. Unlike HMO strategies that will not cover any portion of your expense if you seek out-of-network care (other than in a covered emergency), you can get out-of-network care when traveling out of your regular strategy network area with a PPO policy.
Cost-conscious individuals must consider a few drawbacks to PPO plans that might make getting care more expensive. While they're flexible and hassle-free, PPO plans have higher premiums. According to KFF, PPO strategies had the greatest annual premiums compared to HMOs and point-of-service strategies (POS) in 2023. You'll also need to pay more costly medical costs if you get care from an out-of-network company.
If you do have a deductible, it's likely to be more costly than other strategy types. While your insurer will share the expense with you, you'll likely pay a greater coinsurance portion for out-of-network providers. When you visit an in-network supplier, they'll file your claim to your health insurance company on your behalf.
PPO policyholders might find the claim filing process made complex if they're not used to it or time-consuming if they often need out-of-network care from an expert. In 2023, the typical yearly premium for a group PPO strategy was $8,906 for self-only protection and $25,228 for family coverage2. Employers contributed $7,399 towards a self-only strategy, and employees contributed $1,507.
Evaluating PPO and HMO Insurance
The typical deductible for PPO plans was $1,281. As mentioned above, PPO plans purchased on the ACA markets likewise have a maximum out-of-pocket limit of $9,450 for self-only coverage and $18,900 for family plans.

Yes No Yes No Some plans do. Many plans do. Whether you have an HMO or PPO plan, you can utilize a health repayment arrangement (HRA) to lower out-of-pocket medical expenses.
Insurance in Orange CAOnly companies can launch and contribute toward an HRA. Employers use an HRA to give their workers a monthly allowance to spend for medical costs. As soon as a worker purchases an eligible product or service, they send paperwork revealing evidence of purchase, and their company compensates them as much as their allowance quantity.
Maximizing IUL Growth Benefits for Retirement
Staff member reimbursements will be tax-free if their private health insurance offers minimum vital protection (MEC). Companies can reimburse employees for out-of-pocket expenses and medical insurance premiums, including those for an HMO or PPO strategy. Private protection HRA (ICHRA): An ICHRA is also a stand-alone HRA, however it's offered to companies of all sizes and has no contribution limits.
But, they should have a qualifying kind of specific health coverage to take part. Companies can set various allowances based upon employee classes for included customization. Group protection HRA (GCHRA): Also called an incorporated HRA, a GCHRA is for employers of any size who offer a group health insurance. Only staff members registered in their employer's group strategy can get involved.
While they have no optimum contribution limits, the internal revenue service does not allow repayments for regular monthly premiums. No matter whether it's utilized in coordination with an HMO or PPO strategy, there's an HRA that can help workers pay for their out-of-pocket medical costs and, often, their health insurance coverage premiums. An HRA is a popular alternative option over conventional health advantages due to the fact that they're budget-friendly for employers and versatile enough for every single staff member.
Securing Burial Insurance to Support Seniors
An HMO might be your finest bet if you're looking for a strategy with a low premium. Nevertheless, a PPO strategy supplies extra flexibility if you require more control over your health care. That's why investigating these plans thoroughly, including their pros, cons, and typical costs, is the very best primary step you can take previously making a choice.
(MEC). (ICHRA): An ICHRA is also a stand-alone HRA, however it's offered to companies of all sizes and has no contribution limits.
They need to have a certifying type of private health protection to get involved. (GCHRA): Also understood as an incorporated HRA, a GCHRA is for companies of any size who offer a group health strategy. Only employees registered in their company's group strategy can get involved.
Why Term Life Protects Family Wealth
While they have no maximum contribution limits, the internal revenue service does not enable repayments for month-to-month premiums. No matter whether it's utilized in coordination with an HMO or PPO plan, there's an HRA that can help workers pay for their out-of-pocket medical costs and, in some cases, their medical insurance premiums. An HRA is a popular alternative choice over traditional health benefits due to the fact that they're budget-friendly for companies and versatile enough for every single staff member.
An HMO may be your best option if you're searching for a strategy with a low premium. A PPO strategy offers extra versatility if you need more control over your healthcare. That's why looking into these plans thoroughly, including their pros, cons, and average expenses, is the very best primary step you can take before deciding.

Latest Posts

Comparing Term and Whole Life Policy Basics
Current Term Life Insurance Prices for Families
Best Medigap Coverage for 2026